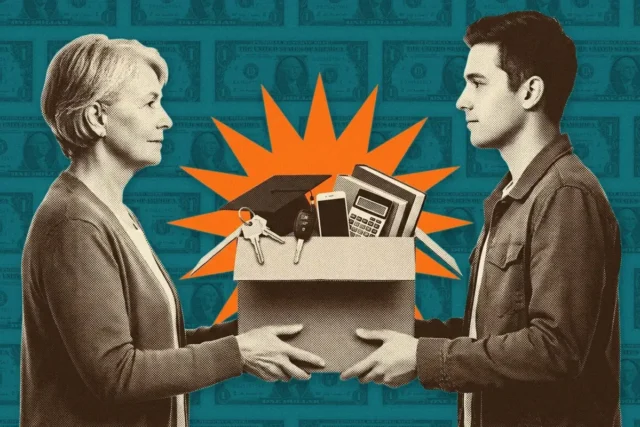
Having kids is expensive, and the financial obligation rarely ends when they turn 18. From helping with rent to bailing their grown kids out of a financial bind, parents sometimes find themselves opening their wallets long after the college tuition bills were supposed to end.
In 2024, about 2.6 million parents gave a combined $26.6 billion to adult children age 21 and older who lived outside their households, according to the U.S. Census Bureau. The median amount parents gave was $4,725 over the course of the year.
And the “bank of mom and dad” has become a staple in modern family life. TD Bank’s 2026 Love & Money Survey found that 71% of respondents had provided financial help to a loved one, whether to cover unexpected expenses, housing costs or other bills.
But for parents nearing retirement, that generosity can come at a cost. Helping adult children financially could mean dipping into savings, cutting back on retirement contributions or even taking on debt.

So how can parents help without risking their own financial futures? Here are five ways to help.
1. Figure out what you can afford to give
Before you hand over any money, take a look at your own financial picture. That means accounting for your retirement savings, expected retirement income, healthcare costs and other expenses you’ll need to cover down the road.
“The first question isn’t how much your adult child needs,” says Pam Krueger, founder and chief executive officer of Wealthramp. “It’s how much you can afford to give without putting your own financial security at risk.”
In other words, don’t let a child’s immediate financial problem become your long-term one. Consider how much you can comfortably contribute after covering your own expenses, maintaining emergency savings and staying on track for retirement. If helping with rent means pausing your 401(k) contributions or dipping into money you’ve been saving for retirement, you may need to offer less — or find another way to help.
And be careful about financial commitments that don’t necessarily involve handing over cash. Co-signing a loan, for example, means you could be on the hook for repaying the debt if your child doesn’t. Taking money from retirement accounts can also mean losing future investment growth and potentially facing taxes or penalties.
2. Set boundaries
A one-time assist can quickly turn into a recurring problem if you’re not clear about long-term expectations. Before you agree to help, decide how much you’re willing to contribute, for how long and what you expect from your child in the meantime.
“You can be generous without making an open-ended financial commitment,” Krueger says. “This is less about financial planning and more about teaching your kids how to respect financial boundaries because someday, they’re going to set their limits for themselves.”
For example, if your grown-up kid is between jobs, you might offer to cover a specific expense for two months rather than promise to help with bills indefinitely. No matter the expense, agree on whether you’re making a one-time contribution or willing to provide additional support — and under what circumstances. Being specific upfront can help prevent an arrangement from becoming a source of tension later.
It’s also worth clarifying whether the money is a gift or a loan. If you expect to be paid back, agree on the repayment terms before handing over any money.
3. Focus on what will help most
If you’re going to help your adult child financially, focus on expenses that could help them get on better financial footing. That could mean helping with a security deposit so your child can move closer to a better-paying job or contributing toward high-interest debt. You might also pay a bill directly, such as a medical expense or tuition, instead of handing over cash.
“I’d much rather see parents make a one-time contribution that helps their child move forward than become a permanent source of monthly income,” Krueger says.
The key is to understand what the request is before deciding to help. If your child is struggling because of a temporary setback, some financial help here and there may be enough to get them back on track.
But if they’re regularly spending beyond their means, covering another month of expenses may only prolong the problem. For example, helping pay down credit card debt won’t do much good if your child keeps adding new balances they can’t pay back.
4. Help them build better money habits
Your kids may be grown, but there’s still room for a little parental guidance — especially when it comes to money. Instead of immediately covering a shortfall, offer to help your kid figure out what’s throwing off their budget, how to tackle debt responsibly or how to start building savings little by little. The goal is to give them tools they can use, preferably without writing a check.
“Every request for money is an opportunity to teach your kids something, whether your answer is yes or no,” Krueger says.
That might mean sitting down together to review how much money is coming in, where it’s going and whether they can cut back on expenses. You could also help them develop a debt repayment plan or set a realistic savings goal.
The idea isn’t to lecture your child about every purchase or take control of their finances. Money conversations can be uncomfortable, after all. TD Bank’s survey found that 59% of respondents occasionally felt scared or embarrassed to discuss their finances openly with someone else.
5. Know when to say no
Every kid’s favorite one-word sentence: No.
As much as you may want to spare your child a financial headache, there are times when saying yes could create one for you. When helping puts your own retirement at risk, it’s time to say no, Krueger says.
It may also be time to draw the line if you repeatedly cover the same expenses without seeing your child take steps to address the problem or if their requests force you to put off your own financial goals.
Be honest about why you can’t help, too. If you can’t afford to help without compromising your retirement, say so. Your child might not love hearing it, but saying no now can help prevent a much harder financial conversation down the road.
“You can love your kids, help them through hard times, and still say no to financial requests you can’t afford. Those things aren’t mutually exclusive,” Krueger says.
Disclaimer
Artificial Intelligence Disclosure & Legal Disclaimer
AI Content Policy.
To provide our readers with timely and comprehensive coverage, South Florida Reporter uses artificial intelligence (AI) to assist in producing certain articles and visual content.
Articles: AI may be used to assist in research, structural drafting, or data analysis. All AI-assisted text is reviewed and edited by our team to ensure accuracy and adherence to our editorial standards.
Images: Any imagery generated or significantly altered by AI is clearly marked with a disclaimer or watermark to distinguish it from traditional photography or editorial illustrations.
General Disclaimer
The information contained in South Florida Reporter is for general information purposes only.
South Florida Reporter assumes no responsibility for errors or omissions in the contents of the Service. In no event shall South Florida Reporter be liable for any special, direct, indirect, consequential, or incidental damages or any damages whatsoever, whether in an action of contract, negligence or other tort, arising out of or in connection with the use of the Service or the contents of the Service.
The Company reserves the right to make additions, deletions, or modifications to the contents of the Service at any time without prior notice. The Company does not warrant that the Service is free of viruses or other harmful components.